
Key Takeaways
What an automated land estimate is, what feeds it, and the regulatory gap that explains why it is a starting point rather than an answer.
- AI land valuation applies an automated valuation model to raw land, producing an instant estimate from comparable sales and parcel attributes.
- The federal AVM quality-control rule that took effect on 1 October 2025 applies only to mortgages secured by a consumer’s principal dwelling, so land sits outside all five of its standards.
- Below $400,000 residential or $500,000 commercial, a regulated lender is not required to obtain an appraisal at all, only an evaluation.
- Land is the hard case for any model because parcels are unique and comparable sales are sparse, so confidence falls fastest exactly where land is cheapest.
- The estimate is worth having. It is a range to start from, checked against a state per-acre baseline and then verified on the ground.
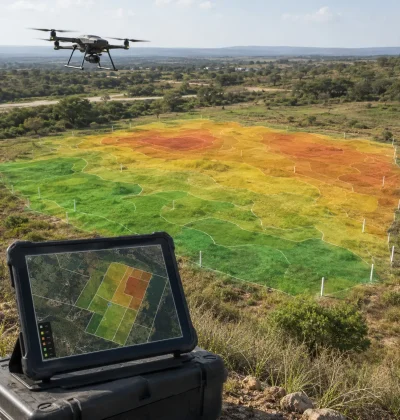
AI land valuation is what happens when the machine learning behind instant home estimates gets pointed at raw and vacant land. Instead of waiting weeks for an appraiser, you get a number in seconds, built from comparable sales, location, acreage and a stack of parcel attributes.
This covers what the technology actually is, what data feeds it, why land is harder than housing, and the specific regulatory reason an automated land number carries less weight than the same number on a house. For the wider picture of what software does in a land sale, start with our guide to AI tools for selling land.
Quick verdict: use an instant estimate to get into the right range fast, because that is genuinely what it is good at and it costs you nothing. Then check it against a per-acre baseline for your state, and verify access, zoning and buildability yourself before the number becomes a price. An automated land estimate is informational, it is not a certified appraisal, and the section below explains exactly why that distinction has a legal shape. This is general information, not financial or legal advice.
What Is AI Land Valuation, Exactly?
It is an automated valuation model pointed at land.
An automated valuation model, usually shortened to AVM, is software that estimates what a property is worth from data rather than from an inspection. Mortgage lenders and consumer real estate sites have used them on houses for years. Applied to land, the model learns how attributes like acreage, location, road frontage and utility access relate to recorded sale prices, then applies those learned patterns to a parcel it has never seen.
The output is a value estimate, usually with some indication of confidence. It is not an opinion of value written by a person who stood on the property.
That difference is the whole subject. An appraiser drives to the site, inspects it, forms a judgment and takes professional responsibility for the result over days or weeks. A model does the statistical part in seconds and takes responsibility for nothing. Both are answering the same question and they are not interchangeable.
What Data Does It Actually Use?
Comparable sales first, then everything that explains the differences between them.
Recent sales of similar nearby parcels anchor almost every estimate. On top of that, models pull structured attributes: acreage, road frontage, utility availability, zoning and permitted use, topography, and whether the parcel has legal access at all.
Many systems then layer in spatial data, tying each parcel to mapped flood zones, wetlands and terrain. Soil quality matters on anything agricultural, and the USDA’s Web Soil Survey is the public source for it, covering more than 95 percent of the nation’s counties as the authoritative record.
The rule is simple: the more clean, relevant, recent data a model has about a parcel and its neighbours, the better the estimate. Which is precisely why land is the hard case.
Why Is Land Harder for a Model Than a House?
Because the data thins out exactly where land gets interesting.
Automated models work best on repetitive housing stock, where a three-bedroom house on a street of three-bedroom houses has fifty near-identical comparables within a mile. Raw land is the opposite. Parcels differ in size, shape, access, topography, water, zoning and use, and a five-acre lot may have no genuine comparable within miles.
The thinner the sales data, the more the model is extrapolating rather than measuring. And sales data is thinnest in remote rural counties, which is where a large share of vacant land actually sits. Confidence therefore falls fastest in exactly the places where an owner is most likely to have no other way to price the parcel.
There is also the physical problem. No model sees the ground. It cannot tell you the access road washes out in spring, the neighbour disputes a boundary line, or the buildable area fails a perc test. Those facts often decide the real value, and our guide to how AI land valuation works goes into what the model is and is not computing.
Is There Any Standard an AI Land Estimate Has to Meet?
For a house, yes. For bare land, no, and the reason is written into the rule.
Six federal agencies, the CFPB, OCC, Federal Reserve, FDIC, NCUA and FHFA, issued Quality Control Standards for Automated Valuation Models, which took effect on 1 October 2025. Institutions using AVMs must adopt policies designed to:
- “ensure a high level of confidence in the estimates produced by AVMs”
- “protect against the manipulation of data”
- “seek to avoid conflicts of interest”
- “require random sample testing and reviews”
- “comply with applicable nondiscrimination laws”
Now read the scope. The rule applies to “mortgages secured by a consumer’s principal dwelling.”
Vacant land has no dwelling on it. So an automated valuation of a parcel falls outside all five of those standards. There is no federal requirement that a land estimate reach any confidence level, no obligation to protect the data behind it, no conflict-of-interest rule, no mandated sample testing, and no nondiscrimination compliance attached to the model itself.
That is not an argument against using one. It is the reason the output is informational, stated precisely rather than vaguely. It also applies to every provider equally, including this one.
What it changes is the question you should ask. Rather than asking whether an estimate is accurate, ask what it was built from: how many comparable sales the model found near your parcel, how recent those sales are, and how similar they are in acreage, access and permitted use. A provider that will answer those three questions is telling you something. One that only shows a confident-looking figure is not.
It also explains why two tools can hand you numbers thousands of dollars apart on the same parcel and neither is doing anything wrong. Without a common standard to meet, they are free to weigh different data differently, and on thin rural comparable sets that freedom shows up as a wide spread.
When Does a Land Deal Even Require an Appraisal?
Less often than most buyers assume, which is the other half of the picture.
Federal rules set transaction thresholds below which no appraisal is required. Under 12 CFR 323.3, an appraisal is not required where “the transaction is a residential real estate transaction that has a transaction value of $400,000 or less” or “a commercial real estate transaction that has a transaction value of $500,000 or less.”
Below the threshold, the rule still requires something. “The institution shall obtain an appropriate evaluation of real property collateral that is consistent with safe and sound banking practices.” An evaluation is a lower bar than a certified appraisal, and an automated model is a common way to produce one.
Most vacant land transactions fall under those numbers. So on a typical land deal the automated figure faces neither an appraisal requirement nor the federal AVM quality-control standards. Both facts are public, both are specific, and together they explain the weight an instant land estimate should carry better than any general warning about technology.
AI Estimate or Appraisal: What Is Each One For?
Different jobs, and most land transactions need the first far more often than the second.
| AI land estimate | Licensed appraisal | |
| Speed | Seconds | Days to weeks |
| Cost | Free or low | Depends on scope, acreage, complexity and region |
| Physical inspection | None | Yes |
| Condition and access verified | No | Yes |
| Covered by the federal AVM rule | Not on land, which has no dwelling | Not applicable, it is a human opinion |
| Standing | Informational | Certified, accepted by lenders and courts |
| Best use | Pricing, filtering, sanity-checking an asking price | Lending above the threshold, disputes, estate and tax matters |
Anyone quoting a flat national price for a land appraisal is guessing. Cost moves with acreage, access, complexity and how far the appraiser has to drive, so get a quote for your parcel rather than a figure from an article.
The question of whether the model will ever take over the appraiser’s role entirely is a separate one, and our page on whether AI can replace a land appraiser works through it.
How Should You Use an AI Land Estimate?
As the first of three steps, never as the only one.
Step one, get the range. Run the estimate. It costs nothing and it stops you anchoring to a number you invented or one a buyer gave you.
Step two, sanity-check it against something independent. USDA’s 2026 Land Values summary publishes per-acre averages by state and land type. Your county will differ, but an estimate landing far outside that range for your land type is worth questioning before you build a price on it.
Step three, verify what the model cannot see. Legal access, zoning and permitted use, buildability, boundaries. These are the facts that move a land price most and the ones no model has.
For sellers, that sequence produces a defensible asking price. Overpricing is the most common reason a parcel sits unsold, and an estimate checked against comparable listings is a better starting point than a hope. For buyers it works defensively: browse land listings at similar acreage in the same county and see whether the asking price is anywhere near the data.
Our guide to price your parcel sets out the full pricing workflow once you have the number.
What Do People Get Wrong About It?
Three things, in order of how much they cost.
Treating the estimate as a price. It is a statistical estimate built from past sales, not an offer. The market can land well above or below it, and on thin comparable data it can be badly off in either direction.
Assuming technology reduces the need for due diligence. On land it increases it, because the model is silent on precisely the issues that kill land deals. Access, boundaries and buildability are still found by a person.
Assuming every estimate carries the same weight. Two tools can disagree sharply on one parcel because they use different data and different models, and neither is bound by the federal quality standards on land. A confident-looking number in a data-poor rural county deserves far more scepticism than one in an active market.
Behind all three sits the same habit: reading a number without asking what is behind it. The reasonable question to ask any automated estimate is how many comparable sales it found, and how recent they were. For the full method of building your own number, see what your land is worth.
Get the Number, Then Check It
An instant estimate is the cheapest useful thing in land pricing. It is also the least accountable, and both of those are true at once.
Start with the range. Get an estimate first, then verify the things a model cannot see.
Frequently Asked Questions
Is AI land valuation the same as a home estimate?
It is the same class of technology applied to a different asset. Consumer home estimates are automated valuation models built on machine learning, and AI land valuation points the same approach at vacant parcels. Land has far fewer comparable sales and far more unique attributes, so land estimates are harder to pin down than home estimates.
How accurate is AI for valuing raw land?
It varies with the data. Where recent comparable sales exist nearby, an estimate lands in a useful range. On remote or unusual parcels with few comparables, accuracy falls sharply because the model has little to learn from. Treat any automated land value as a first screen and confirm it against local comparable sales.
Is an AI land estimate regulated?
Not on bare land. The federal quality-control rule for automated valuation models, effective 1 October 2025, applies to mortgages secured by a consumer’s principal dwelling. Vacant land has no dwelling, so a land estimate falls outside all five of the rule’s standards, including its confidence and testing requirements.
Can AI replace a land appraiser?
Not for lending above the federal threshold, for courts, or for estate and tax matters, where a certified human opinion is required. An automated model never inspects the property and carries no professional accountability. In practice the two work together, with the model handling speed and the appraiser handling inspection and certification.
Does a land purchase always need an appraisal?
No. Federal rules exempt residential real estate transactions of $400,000 or less and commercial transactions of $500,000 or less, though the institution must still obtain an appropriate evaluation consistent with safe and sound banking practices. Most vacant land transactions fall below those thresholds, so an evaluation rather than an appraisal is common.
Resources and Further Reading
- CFPB and five other agencies: Quality Control Standards for Automated Valuation Models sets the five AVM quality factors and limits the rule to mortgages secured by a consumer’s principal dwelling, effective 1 October 2025.
- 12 CFR 323.3, Appraisals required sets the $400,000 residential and $500,000 commercial thresholds and the evaluation requirement below them.
- USDA NRCS Web Soil Survey is the authoritative public source of soil data feeding land valuation, covering more than 95 percent of US counties.
- USDA NASS Land Values 2026 Summary publishes per-acre averages by state and land type as an independent check on any estimate.


