Can You Use a USDA Loan to Buy Vacant Land? Four Programs Compared
Not the USDA loan most people mean. Section 502 Guaranteed requires a dwelling you occupy. Two other USDA programs reach land, with hard limits.
Not the USDA loan most people mean. Section 502 Guaranteed requires a dwelling you occupy. Two other USDA programs reach land, with hard limits.
No public dataset sets land contract down payments. Ohio shifts the seller’s remedy at 20 percent paid, Texas at 40 percent, Michigan at 50.
Price a land note above the IRS Applicable Federal Rate, 5.12 percent long-term in September 2026, and above the 6.76 percent mortgage benchmark.
Yes, through owner financing. The seller sets the terms, so the questions that matter are who holds title and what happens if you miss a payment.
Name the parties, describe the land by its legal description, set price, payments, default and title transfer, then record it.
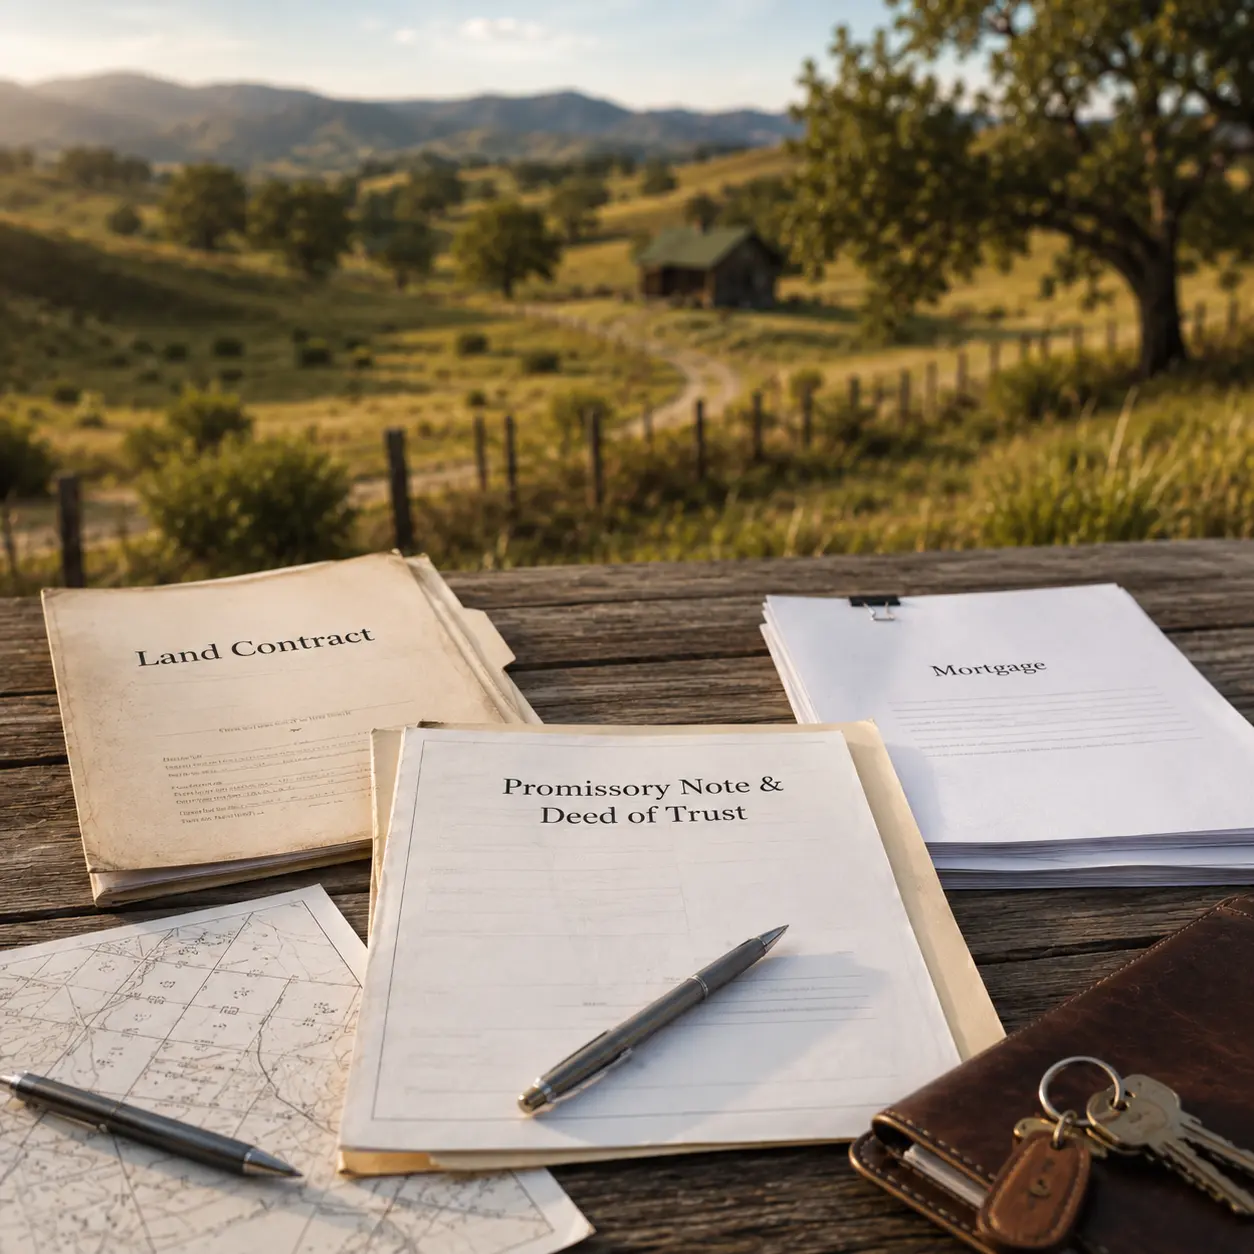
A land contract has the seller finance you and keep legal title until you pay in full; a mortgage has a bank lend the money and give you title with a lien.
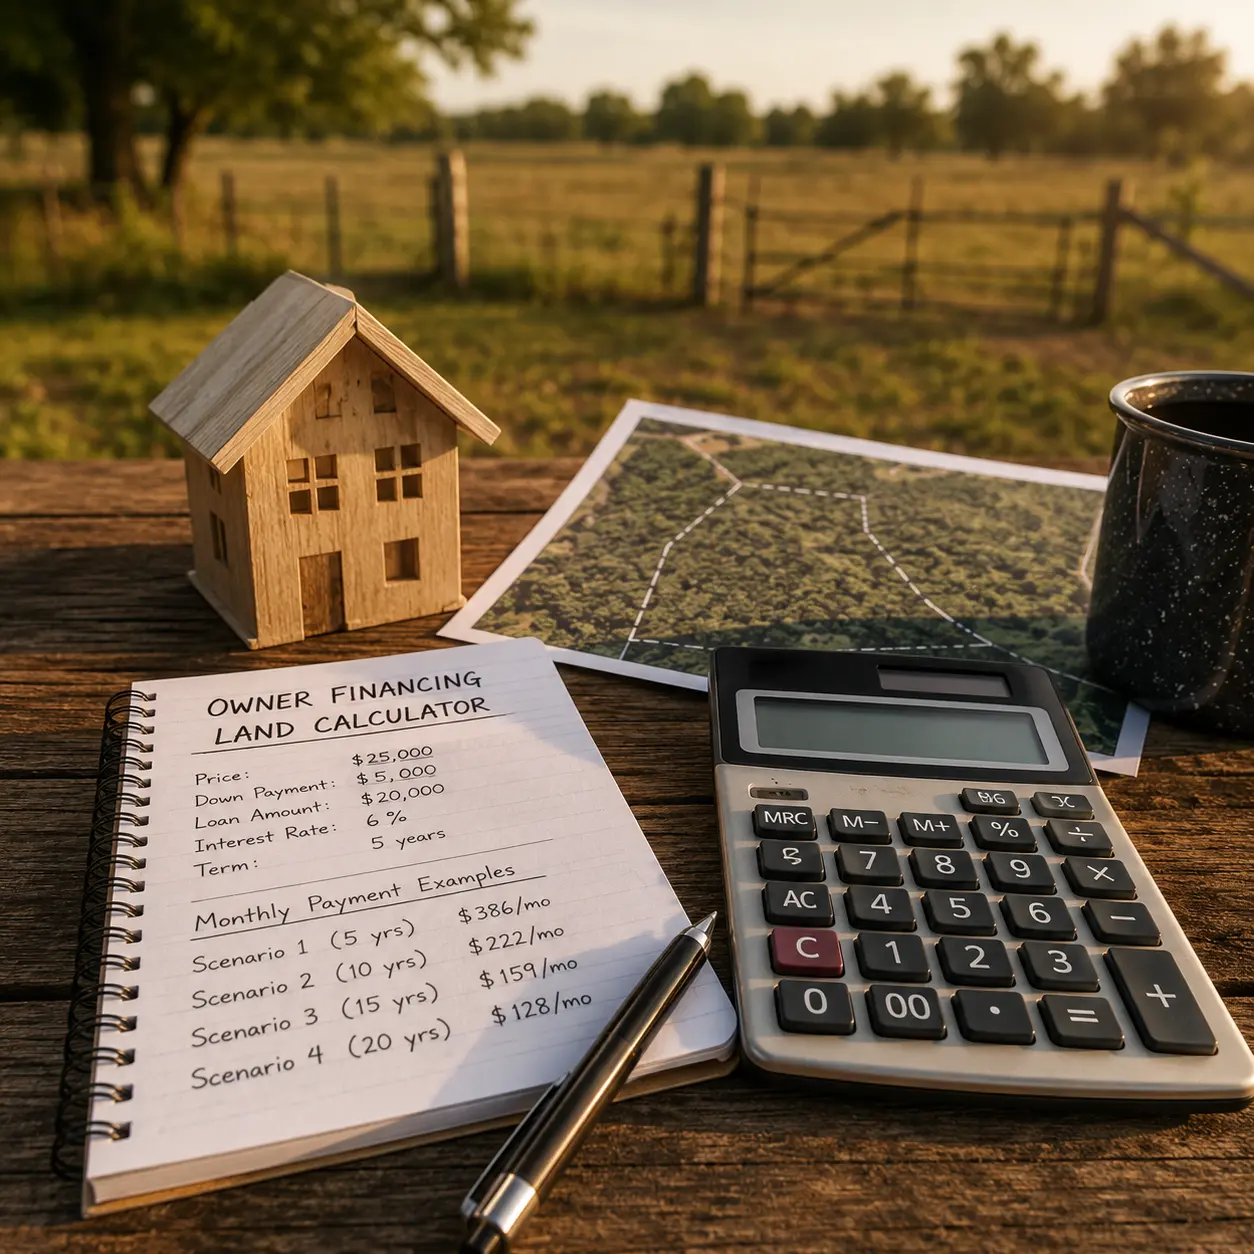
An owner financed land payment uses standard amortization. $40,000 financed at 9% over 10 years is $506.70 a month.
To offer seller financing on land, set the price and down payment, fix the rate and term, choose your instrument, screen the buyer, then record everything.
Owner financing sells land faster by expanding your buyer pool, because most buyers cannot get a bank loan on raw land, so financing it yourself reaches more of them.
Find owner financed land listings on land marketplaces that filter for seller financing, so you buy directly from the owner with no bank approval or credit check.